AV Rental Insurance: What Planners Should Ask
A corporate event planner's guide to certificates of insurance, who is responsible for rented AV gear, and the vendor questions to ask before you sign.
Why AV Insurance Trips Up Corporate Planners
Insurance around an AV rental comes from two sides. The vendor carries its own policies, typically general liability, workers' compensation for its employees, and often equipment (inland marine) coverage for its gear. The renter may carry event liability insurance and coverage for the rented equipment while it is in their hands. A certificate of insurance (COI) shows that a vendor's policy exists; venues often ask for one once an event is booked.
You've booked the venue, locked the speaker list, and picked a caterer. Then two weeks before the event, the venue asks for a COI from your AV vendor, naming the venue as an additional insured party with specific liability limits. If your AV company can't produce one fast, or the limits don't match what the venue requires, you're stuck renegotiating on a deadline that doesn't move.
The U.S. Small Business Administration describes general liability insurance as protection against financial loss from bodily injury, property damage, medical expenses and lawsuits, while damage to a business's own property is a matter for separate property coverage. For equipment that moves between locations, The Hartford describes inland marine insurance as coverage that "helps protect tools, equipment and property that move from place to place," including items "damaged, lost or stolen while in transit or at a job site." If a truss drops, a cable trips a guest, or an LED wall gets damaged in transit, which policy applies, and whether it pays, depends on the contract and on each policy's terms, limits and exclusions.
Asking these questions during the RFP stage, before signing, leaves time to fix a gap or change vendors. This guide walks through what a certificate of insurance should contain, who carries what risk in an AV rental agreement, and the specific questions to put in front of any vendor before you sign a contract for AV rental equipment or services.
The goal is knowing what to look for, so you can tell which vendors can back up their bid with documented coverage. This is general information, not insurance or legal advice; your broker and your venue contract are the authorities for your event.
What a Certificate of Insurance Should Actually Show
A certificate of insurance is a short summary, issued by the vendor's insurer or agent, listing the vendor's policies, limits and dates. It's not the policy itself: The Hartford notes that its certificates "only establish that the insurance policy exists." Here's what to check on any COI an AV vendor sends you:
- General liability limits: Venues set their own minimums, usually stated per occurrence and in aggregate. Some larger venues ask for higher limits; check the insurance clause in your venue contract.
- Additional insured endorsement: The venue (and sometimes you, as the event organizer) should be named as an additional insured, not just listed as a certificate holder. The Hartford's guide to certificates of liability insurance says being a certificate holder "doesn't mean they'll have legal rights on your liability insurance coverage"; to extend liability coverage to a client, "you have to add them as an additional insured on your policy," meaning the vendor must add them. Ask to see the endorsement wording, not just the certificate.
- Equipment/inland marine coverage: This type of policy is designed to cover the vendor's gear in transit and on-site. Whether a particular loss, such as a speaker damaged during load-in, is covered depends on the policy's terms and exclusions, and on who was responsible under the rental contract.
- Workers' compensation: The California Department of Industrial Relations says California employers "are required by law to have workers' compensation insurance, even if they have only one employee." If the vendor's own crew is on-site rigging truss or running cable, ask for proof of that coverage. It covers the vendor's employees; it is not a promise that nobody else can be named in a claim.
- Policy expiration date: COIs get requested well before an event and the policy can lapse by event day. Always check the expiration date against your event date, not just the issue date.
Certificates come from the vendor's insurer or agent. If a vendor can't tell you when a certificate will arrive, or can't state their coverage limits, note that before you sign anything.
Illustration: reading the paperwork before you sign. Photo: Gabrielle Henderson / Unsplash.
Who's Liable When Equipment Fails or Gets Damaged
Responsibility in an AV rental involves three parties: the vendor, the venue, and the event organizer (you, or your company). Your rental contract and venue contract set out who is responsible for what, so read both before the event rather than after something breaks. Four scenarios are worth thinking through for any corporate event:
Equipment fails during the event. If a wireless mic drops out mid-presentation or a projector fails, what the vendor owes you is set by the rental contract: some promise a replacement, some a refund, some only a reasonable effort. That makes it a service question as much as an insurance one, which is why asking about backup equipment during the RFP stage matters as much as asking about insurance.
Equipment gets damaged by a guest or third party. If someone at your event knocks over a speaker stand or spills a drink into a mixing board, who pays depends on the rental contract; many rental agreements, including ours below, make the renter responsible for equipment while it is in their possession. Some vendors offer a damage waiver as an add-on, similar to a rental car's collision waiver; ask what it costs and what it excludes.
A rigging or structural failure causes injury. This is the scenario where coverage matters most. If truss, lighting, or a mounted screen fails and someone gets hurt, the vendor's general liability policy may respond, depending on its terms, limits and exclusions and on whether the venue or your company was added as an additional insured. Claims can also be made against the venue or your company, which is one reason organizers carry their own event insurance. Ask your broker to confirm which policies would apply to your setup.
Weather or power failure cancels the event outdoors. This is a contract issue, not a liability one: check your AV rental agreement's cancellation and force majeure clauses, especially for outdoor events, so you know what's refundable versus what's a sunk cost.
How VENEGEEST's own terms handle this. Our rental terms make the client responsible for rented equipment from delivery or pickup until it comes back, and damaged, defective or incomplete returns are charged at repair or replacement cost. We strongly encourage clients to carry event insurance that covers rented equipment against theft, damage and loss. An optional Equipment Protection Plan is available at 10% of the rental total and covers accidental damage, excluding negligence and theft. Our liability is limited to the rental fees paid for the equipment in question and excludes indirect or consequential losses such as event cancellation costs, and if equipment malfunctions during a rental we make every reasonable effort to provide a replacement. The client is also responsible for any venue-specific permits or approvals the installation needs. Read the full terms of service before you book.
A clear, written contract that says who is responsible for what helps everyone, and the insurance behind it is worth checking as carefully as the contract. A certificate on its own does not give its holder rights under the vendor's policy; if you or your venue need that, it takes an additional insured endorsement.
Questions to Ask Before You Sign
Put these directly to any AV vendor during the quoting stage, before you're locked into a contract. A vendor who answers clearly and quickly is telling you something about how they run their business, not just about their insurance.
- Can you send a current certificate of insurance naming our venue as additional insured? Ask for this in writing, and get it before signing, not after.
- What are your general liability limits, and do they meet our venue's minimum? Check this against your venue contract's insurance clause directly; some larger venues ask for higher limits.
- Do you carry equipment/inland marine coverage separate from general liability? This type of policy is designed for the gear itself; ask what it excludes.
- What happens if your equipment fails during the event? Ask about backup gear on-site or on-truck, and whether there's an on-site tech during the event, not just for setup and teardown.
- Is a damage waiver available, and what does it cover? Understand what you're still on the hook for if it isn't purchased.
- Who is the point of contact if something goes wrong day-of? Get a name and a phone number for event night, not just the office line.
A well-run pre-event AV planning checklist should include a line item for confirming insurance alongside equipment specs and load-in times, not as an afterthought two days before doors open. Building this into your standard vendor intake process means you're never asking these questions under deadline pressure.
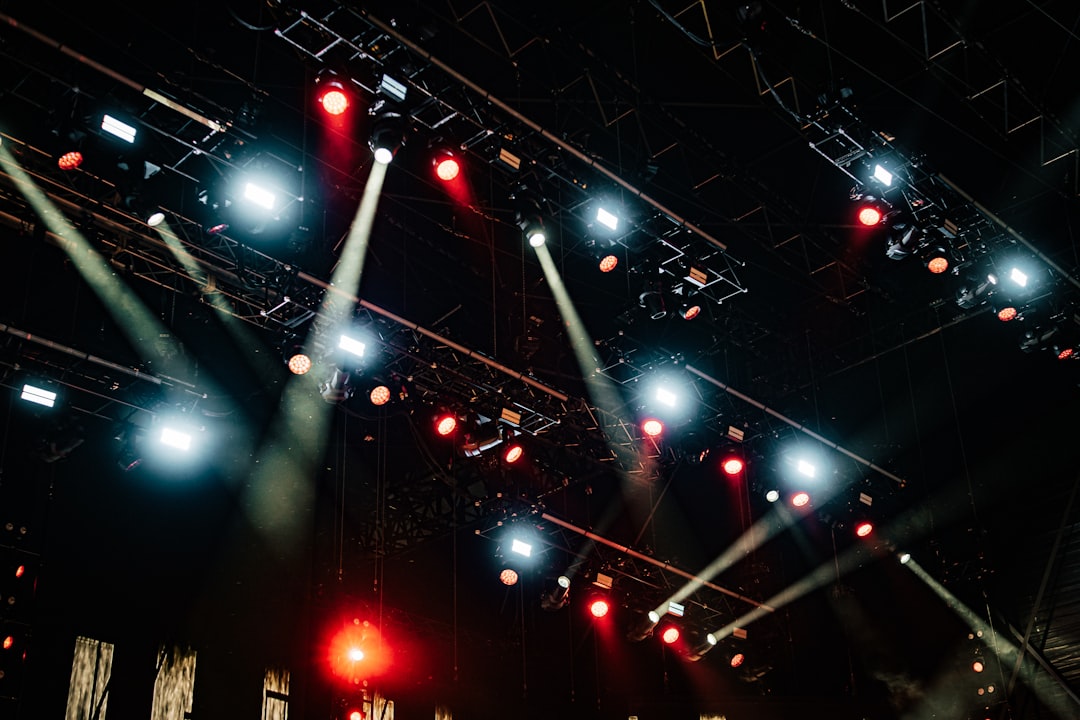
Overhead truss and lighting: the kind of installation where coverage questions deserve extra attention. Photo: Ambitious Studio | Rick Barrett / Unsplash.
Why Rigging and Structural Work Raises the Stakes
Insurance questions matter for every AV rental, but they matter most when the job includes overhead rigging, truss, or mounted structures. A tripod-mounted projector screen puts nothing overhead, unlike a suspended LED wall or a truss system holding moving lights above a crowd.
If your event includes rigging work, ask what training the vendor's crew has for rigging, and ask the vendor's insurer or agent to confirm in writing that the policy covers the rigging work planned for your event. A certificate lists policies and limits, not every exclusion, so it cannot answer that question on its own. Our truss and rigging safety checklist covers the load ratings and inspection steps that should happen before anything goes up, and it's worth reviewing alongside your insurance questions rather than treating them as separate conversations.
FAQ: AV Rental Insurance and Liability
Does my company need its own event insurance if the AV vendor is covered?
It depends on your event's size and your company's risk tolerance. A vendor's policy is written for the vendor's own business, so it is not designed to cover you as the event organizer for incidents unrelated to the vendor's work, like a guest slipping on a wet floor. Ask your company's broker whether you need a separate event liability policy for your event; our own terms strongly encourage renters to carry event insurance that covers rented equipment.
How much does an AV vendor's insurance cost, and does it affect my rental price?
A vendor's insurance premiums are part of its cost of doing business; how that shows up in a quote varies by vendor, so ask. Some vendors, including us, also offer an optional protection plan for the rented equipment as a separate line: ours is 10% of the rental total, covering accidental damage but not negligence or theft. Whatever the quote, ask for the certificate and limits before you compare prices.
What's the difference between a certificate holder and an additional insured on a COI?
A certificate holder receives a copy of the certificate. The Hartford notes that being a certificate holder "doesn't mean they'll have legal rights on your liability insurance coverage"; to extend coverage, the vendor has to add them as an additional insured on the policy. If your venue contract asks for additional insured status, confirm it with the vendor's insurer or agent and ask for the endorsement.
Can I ask to see the actual insurance policy instead of just the certificate?
You can ask; the vendor decides what it shares. At a minimum, ask for the certificate plus any endorsement that names your venue or company, and if you have questions about either, contact the insurer or agent listed on the certificate directly.
What happens if a vendor's insurance lapses between booking and event day?
This is why checking the policy expiration date against your event date matters at booking time, and again shortly before the event. If the vendor's policy renews before your event date, ask for an updated certificate rather than assuming one will arrive.